You Have ₹500. Now What? How to Start Investing in India
You don't need a lot of money to start investing. You just need to
In our previous articles, we learnt how to save money for emergencies and how mutual funds work.
Now let's take the next step.
Imagine you have saved ₹500 and finally decided to invest it.
You search Google for "How to invest in India?"
Suddenly, you're reading about Demat accounts, trading accounts, stockbrokers, NSE, BSE and KYC.
You might wonder, "I just want to invest ₹500. Why do I need so many accounts?"
Let's understand what these accounts are and how you can make your first investment.
First, what is a Demat account?
You already have a bank account where you keep your money.
A Demat account is quite similar, except instead of money, it holds your shares and other eligible securities electronically.
In the old days, people received physical certificates when they purchased shares in a company.
Today, everything is stored digitally.
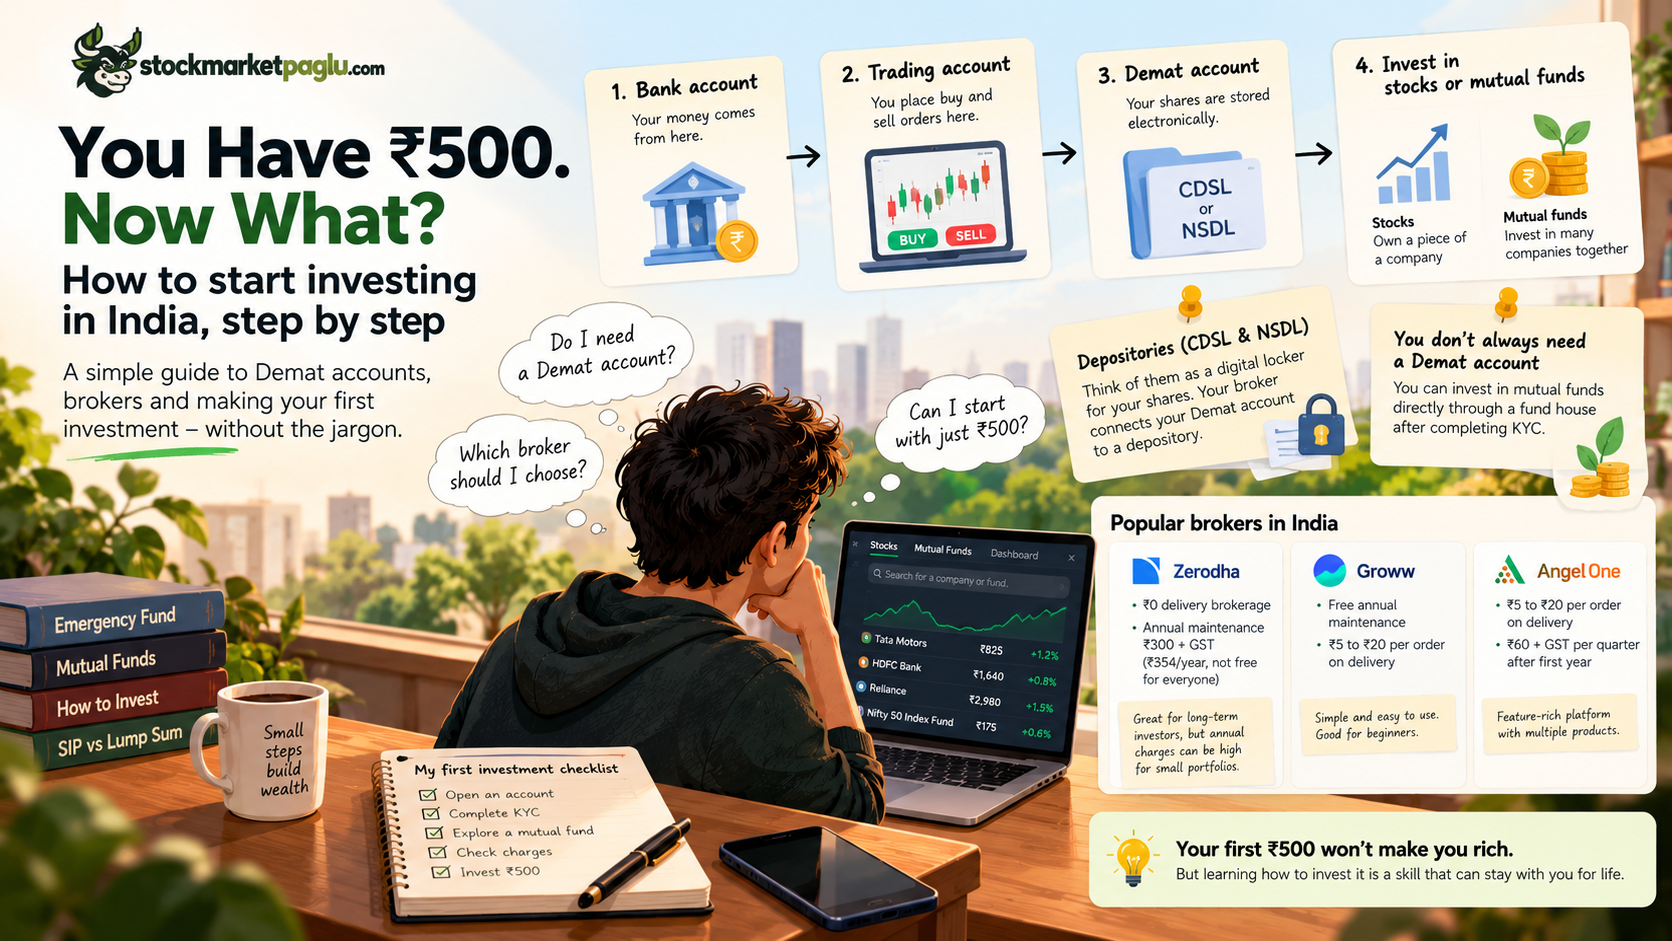
To invest directly in stocks, you'll generally need three things:
- Bank Account: Where your money comes from.
- Trading Account: Used to buy and sell shares on the stock exchange.
- Demat Account: Where your purchased shares are stored electronically.
For example, imagine you want to buy one share of ITC.
You transfer money from your bank account, place the order using your trading account, and once the transaction settles, the share is credited to your Demat account.
Simple, isn't it?
One interesting thing: You don't actually need a Demat account to invest in regular mutual funds. You can purchase mutual fund units directly from a fund house.
But where are your shares actually stored?
You might have heard of two companies called CDSL and NSDL.
What exactly do they do?
Think of a depository as a digital locker for your shares.
Just like a bank maintains records of your money, a depository maintains electronic records of the securities you own.
India has two major depositories:
- CDSL: Central Depository Services (India) Limited.
- NSDL: National Securities Depository Limited.
Let's say you purchase 10 shares of a company through Zerodha.
Zerodha helps you purchase those shares, but your holdings are recorded in your Demat account through a depository such as CDSL.
Your broker or its associated entity acts as a Depository Participant (DP), connecting your Demat account to the depository.
Here's the interesting part.
What happens if your broker shuts down?
Your shares don't simply disappear with the broker. Your holdings remain recorded in the depository system, and you can generally transfer them to another Depository Participant after completing the required process.
Of course, disputes, unsettled transactions or fraudulent activity can still create complications.
The important thing to remember is:
Your broker helps you buy shares. Your depository maintains the record of what you own.
Where do you open these accounts?
You might have heard of Zerodha, Groww, Angel One or Upstox.
These are popular investment platforms that provide access to stock market investing.
They help you open the necessary accounts and place orders.
But who makes sure these companies are following the rules?
Just like we discussed in our mutual funds article, SEBI (Securities and Exchange Board of India) regulates securities market intermediaries in India.
Brokers must follow regulatory requirements, and depositories operate under SEBI's oversight.
This is why you should always choose a SEBI-registered broker.
How do you open an account?
The process is mostly online.
You'll generally need:
- Your PAN card.
- Aadhaar or other accepted identity and address documents.
- An Indian bank account.
- Mobile number and email for verification.
Choose a broker, complete your KYC (Know Your Customer), and follow the account-opening process.
But which broker should you choose?
Let's look at three popular options in India.
1. Zerodha
Zerodha offers a trading platform called Kite and a separate mutual fund platform called Coin.
- Account opening: Free.
- Stock delivery brokerage: ₹0.
- Annual maintenance: Free for the first year. Afterwards, charges depend on your Demat account type and holdings.
The trade-off: No brokerage on delivery-based stock purchases, but Demat maintenance and share-selling charges may apply.
2. Groww
Groww lets you explore mutual funds and stocks through the same platform.
- Account opening: Free.
- Annual maintenance: Free.
- Stock delivery brokerage: Lower of ₹20 or 0.1% per order, with a minimum of ₹5.
The trade-off: No annual maintenance charges, but even a small stock purchase attracts brokerage.
3. Angel One
Angel One provides stock investing, mutual funds and trading tools.
- Account opening: Free.
- Annual maintenance: Free for the first year, with applicable charges afterwards.
- Stock delivery brokerage: Lower of ₹20 or 0.1% per order, with a minimum of ₹5 after promotional benefits expire.
The trade-off: Offers several investing and trading features, but charges and introductory offers need to be checked carefully.
One thing you should know about charges
Imagine you're purchasing one share worth ₹500.
A ₹5 brokerage fee might sound insignificant, but that's already 1% of your investment, excluding taxes and other charges.
And when you eventually sell, additional charges may apply.
This is why I want you to compare brokers before opening an account.
You don't need the platform with the most features. You need one you understand, trust and can afford to use.
Once your account is activated, you're ready to explore your first investment.
Let's invest our first ₹500
Now comes the part we've been preparing for.
You have ₹500. Where should you put it?
Let's look at two options.
Option 1: Investing in mutual funds
Remember the Nifty 50 Index Fund we discussed in our previous article?
It aims to follow the Nifty 50 index, giving you exposure to 50 major Indian companies.
To invest:
- Open your investment platform or a mutual fund company's website.
- Search for a Nifty 50 Index Fund.
- Check the fund's Riskometer, expense ratio and investment details.
- Enter ₹500 if the scheme supports that amount.
- Complete your payment.
Once your investment is processed, you'll receive mutual fund units.
You now own a small portion of a fund investing across several companies.
Of course, their prices can rise or fall, and so can your investment.
Option 2: Buying a company share
Let's say you really like a company and want to become one of its shareholders.
You open your trading app and search for the company.
Imagine its current share price is ₹350.
With ₹500, you could purchase one share, provided you have enough left to cover applicable charges.
You place a buy order, and once it's executed and settled, the share appears in your Demat account.
You now own a tiny piece of that company.
But there's something I want you to remember.
Just because a company's share costs ₹50 doesn't mean it's cheaper or better than a company whose share costs ₹1,000.
A stock's price alone tells you very little about whether it's a good investment.
We'll learn how to understand companies in a later article.
What happens after you invest?
Let's say you invested ₹500.
A few days later, you open the app and see ₹480.
Should you panic?
Not necessarily.
The stock market moves every day. Sometimes your investments will rise, and sometimes they'll fall.
The important thing is to understand why you made an investment and how much risk you're taking.
And please, don't invest money you might need next week.
Remember our emergency fund? That money has a different job.
One last thing
I don't want you to finish this article and immediately buy a random stock.
Instead, here's something you can try today.
Open an investment platform and explore two things:
- A Nifty 50 Index Fund.
- A company whose products you use regularly.
Look at their prices, investment details and risks.
You don't even need to invest immediately.
The goal is to get comfortable with how investing works.
Your first ₹500 might not make you rich. But learning what to do with that ₹500 is a skill that can stay with you for life.
In our next article, we'll understand another interesting question.
Should you invest a little every month, or save up and invest everything together?
Disclaimer: This article is for educational purposes only and is not personalised investment advice. Investments are subject to market risks.
Sources: SEBI Investor Education · CDSL · NSDL · NSE — First-Time Investors
Next on the beginner pathSIP or lump sum? What ₹5,000 a month can actually becomeThis article is for education only and is not personalised investment advice. Returns shown are illustrations, not forecasts. Rules and rates change, so check the latest information and consider a SEBI-registered adviser for decisions about your own money.
We explain Indian personal finance in plain language, show our assumptions and never take money to recommend a product. Read our editorial policy.