Buying Health Insurance? Ask These 6 Questions First
The cheapest policy isn't always the one that saves you money.
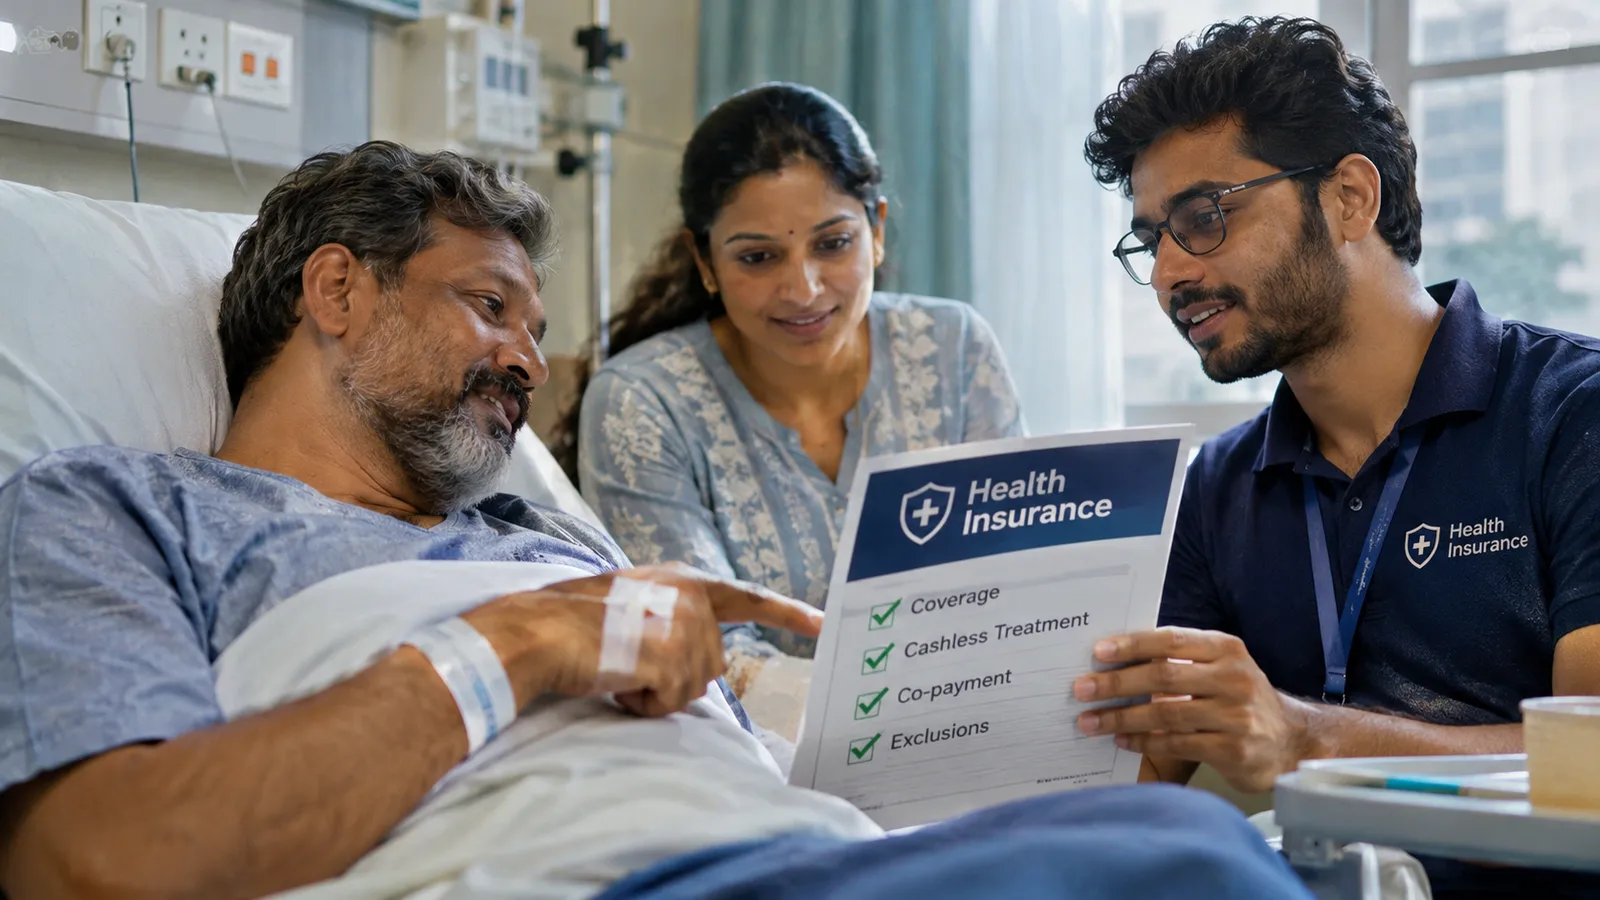
You've decided to buy health insurance.
You search online, and suddenly there are twenty different policies claiming to be the best.
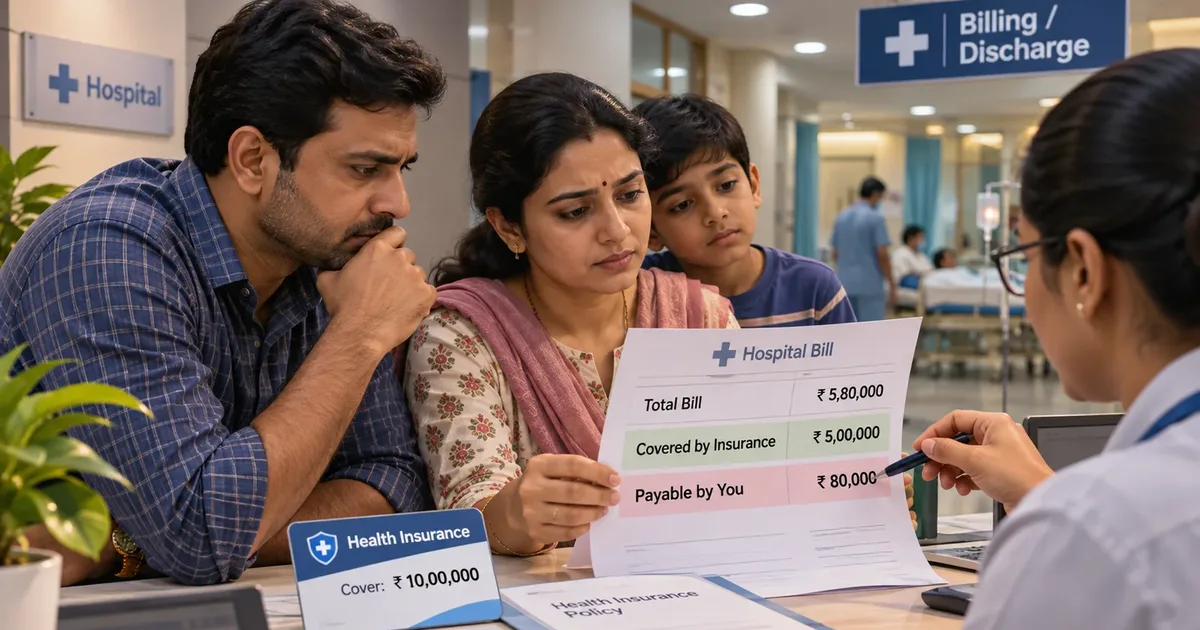
₹10 lakh cover. ₹25 lakh cover. Unlimited restoration. Zero co-pay.
Great. But what does any of it mean?
Before paying anyone, here's what I'd ask.
1. How Much Will I Pay From My Own Pocket?
Ask whether the policy has a co-payment.
If it does, you might have to pay part of an approved hospital bill yourself.
I'd prefer a policy without mandatory co-payment, provided the premium is affordable.
2. Can I Choose Any Hospital Room?
Some policies limit how much they'll pay for a hospital room.
Choose a room above that limit, and you might have to pay extra for more than just the room.
Ask for a policy without restrictive room-rent limits.
3. What Happens to My Existing Medical Conditions?
Already have diabetes, high blood pressure or another health condition?
Your policy might not cover related treatment immediately.
This is called a waiting period.
Always disclose your medical history honestly.
Saving a little on premiums isn't worth creating problems when you need to make a claim.
4. What's NOT Covered?
This might be the most important question.
Check for exclusions, treatment-specific limits and costs the insurer won't pay.
Ask for the Customer Information Sheet (CIS). It's a short document summarising the important terms of your policy.
5. Which Hospitals Can I Actually Use?
Check whether hospitals you would realistically visit have cashless arrangements with the insurer.
Also ask whether your family shares one coverage amount or gets separate coverage.
A ₹10 lakh family floater generally means ₹10 lakh shared among the covered family members.
6. Who Will Help Me During a Claim?
Buying insurance is easy.
Handling paperwork when someone is hospitalised? Not so much.
Ask what help you'll receive if a claim gets delayed or rejected.
And don't assume the advisor can guarantee claim approval. The insurer makes that decision.
Too Confusing? Here's What I'd Do.
I'd book a free consultation with Ditto Insurance.
They help people compare health insurance policies, understand the conditions and select suitable coverage.
You can discuss all six questions with an advisor instead of reading twenty brochures yourself.
Ditto also offers assistance with claims and renewals.
One thing worth knowing: Ditto earns commissions from partner insurance companies when customers purchase policies through it.
Why am I suggesting Ditto then? Simple, because they don't spam.
My suggestion?
Speak to an advisor, shortlist two or three policies, and compare their exclusions, waiting periods and costs before deciding.
And please, don't buy something just because someone says:
"Sir, offer aaj hi valid hai!"
Health insurance is supposed to protect your savings, not become another expensive surprise.
Disclaimer: This article is for education only. Policy conditions vary by insurer and product. Always check the official policy wording before buying.
This article is for education only and is not personalised investment advice. Returns shown are illustrations, not forecasts. Rules and rates change, so check the latest information and consider a SEBI-registered adviser for decisions about your own money.
We explain Indian personal finance in plain language, show our assumptions, never take money to recommend a product and label any referral links. Read our editorial policy.